The Retirement Protection Dilemma
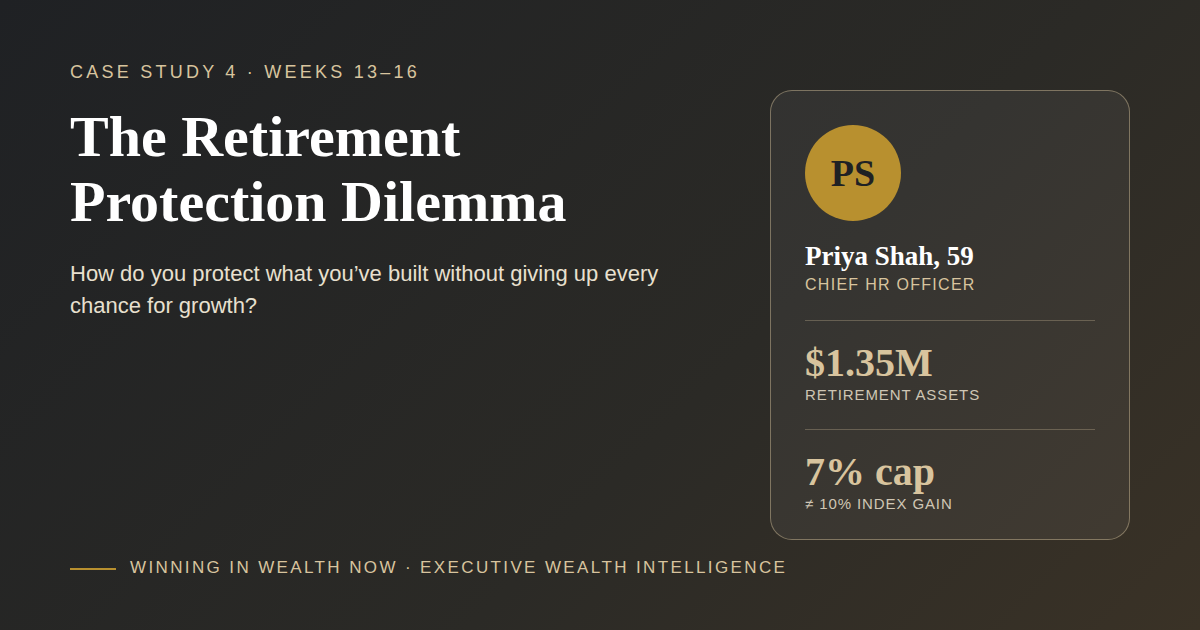
She spent 28 years building her retirement savings. Now she's asking a question she never thought she'd have to ask: How do I protect what I've built without giving up every opportunity for growth?
Priya isn't looking for a financial product. She's looking for greater certainty about her future. She's not afraid of investing. She's experienced market volatility before. But she's approaching a season when the consequences of losses, limited liquidity, and financial decisions that are difficult to reverse deserve more attention.
Companion article: What a Fixed Indexed Annuity Does—and Doesn't Do
Priya Shah, 59
- Career
- Chief Human Resources Officer at a national technology company
- Annual compensation
- $275,000, including incentives
- Retirement assets
- Approximately $1.35 million across retirement and investment accounts
- Family
- Married, one adult daughter
- Retirement goal
- Transition from corporate leadership at 63, with the option to serve on boards and mentor emerging executives
- Financial concern
- Much of her savings remains exposed to market fluctuations
The Retirement Question That Changed How She Thought About Risk
Priya had $1.35 million in retirement and investment assets. But she was no longer comfortable treating every dollar as though she had another 20 years to recover from a major market decline.
Meet Priya Shah.
59 years old.
Chief Human Resources Officer.
Annual compensation of approximately $275,000.
A successful corporate career spanning nearly three decades.
And a retirement date she could finally see on the horizon.
Age 63.
Four years away.
Priya had spent years doing what financially responsible professionals are encouraged to do.
She contributed to retirement accounts.
She invested for long-term growth.
She stayed disciplined through market volatility.
She didn't panic every time the market declined.
But recently, something had changed.
Not her willingness to invest.
Her relationship with risk.
When she was 40, a market downturn felt like something she had time to recover from.
At 59, she was beginning to think about what would happen if a significant decline occurred just before she wanted to retire.
She didn't want to abandon growth.
She wanted to understand whether every part of her retirement savings needed to carry the same level of market exposure.
During a financial conversation, someone mentioned a fixed indexed annuity.
The description sounded interesting.
Potential interest linked to a market index.
Contractual protection against negative index-crediting results.
Possible retirement-income features.
But Priya wasn't ready to make a decision based on a few attractive phrases.
She had questions.
What exactly am I buying?
What am I protected against?
What am I giving up in exchange for that protection?
And perhaps most importantly:
How would this fit into the retirement plan I already have?
Those are the right questions.
A fixed indexed annuity, or FIA, is an insurance contract issued by an insurance company.
It may credit interest based partly on the performance of a specified market index, subject to a formula established in the contract.
But you are not directly investing in the stocks that make up that index.
And the amount of interest credited may be limited by caps, participation rates, spreads, or other contract provisions.
An FIA can have a contractual floor that prevents negative index performance from producing a negative index-interest credit for a given crediting period.
But that doesn't mean the contract eliminates every possible loss or financial risk.
Withdrawals, surrender charges, rider fees, taxes, inflation, and insurer financial strength still matter.
Priya realized the question wasn't:
“Are fixed indexed annuities good or bad?”
It was:
“What problem does this contract solve, and what trade-offs would I accept to solve it?”
Before evaluating any retirement product, identify:
What financial risk are you trying to manage?
How much liquidity do you need to preserve?
What growth or income objective must the strategy support?
What alternatives should you compare?
A financial product should serve your strategy.
Your strategy shouldn't be built around a product.
Priya discovers how a fixed indexed annuity can credit interest when a market index rises—and why the credited interest may be very different from the index's actual return.
The Market Went Up 10%. Why Didn't Her Annuity Illustration Show 10%?
Priya was told a fixed indexed annuity could earn interest linked to the S&P 500.
Then she asked a question that changed the conversation.
“If the S&P 500 goes up 10%, does my money earn 10%?”
The answer was no.
And understanding why was one of the most important parts of evaluating the contract.
Last week, I introduced Priya.
A 59-year-old executive with approximately $1.35 million in retirement and investment assets.
She was exploring whether a portion of her savings should have different risk characteristics as she approached retirement.
Someone had introduced her to a fixed indexed annuity.
But she wanted to understand the mechanics before considering whether it belonged in her plan.
So she began with the interest-crediting formula.
A fixed indexed annuity doesn't typically credit the full return of the market index it references.
Instead, the insurance company uses a contract-defined method to calculate interest.
One common feature is called a cap.
Let's use a hypothetical example.
Suppose Priya is reviewing an FIA with a 7% annual cap on a particular index-crediting strategy.
If the index rises 4% during the specified period, the contract might credit 4%.
If the index rises 10%, the contract would credit 7% under that simplified cap-only formula.
If the index declines 12%, a 0% index-interest floor could result in a 0% interest credit for that period.
| Index change | Illustrative interest credit |
|---|---|
| +4% | 4% |
| +10% | 7% |
| −12% | 0% |
That is not the same as receiving the full market return.
And it doesn't mean all contract values are immune to fees or other reductions.
The contract may also use a participation rate or a spread.
Those provisions can change how much interest is credited.
Priya also discovered another important distinction.
When an index is used for annuity crediting, the calculation generally doesn't include dividends paid by the companies in the index unless the particular index methodology provides otherwise.
So even when an FIA references a familiar index, its credited return can differ substantially from investing directly in a fund that tracks that index.
That isn't necessarily a defect.
It's part of the trade-off.
The insurer provides contract-defined crediting and protection features.
In exchange, the contract limits or modifies the potential interest credited.
Priya's next question was the one I wish more consumers would ask.
“Can you show me the exact formula—and what happens under several different market scenarios?”
Not just the most favorable illustration.
A positive market.
A flat market.
A declining market.
And a period when the contract credits no interest.
If you're evaluating an FIA, ask for a written explanation of:
The index used.
The crediting period.
The cap, participation rate, and spread, where applicable.
The index-interest floor.
Any rider charges or other costs that could affect contract values.
Then request hypothetical examples using the actual contract terms.
Don't evaluate an annuity based only on a headline rate.
Understand the calculation behind it.
Priya understands how interest may be credited. Now she faces a more personal question: If she puts money into an annuity, how much flexibility will she retain if her life changes? We'll examine liquidity, surrender charges, taxes, and what contractual protection does—and doesn't—mean.
What Does “Protected Principal” Actually Mean?
Priya liked the idea of protecting part of her retirement savings from negative index-crediting results.
But then she asked a question that mattered even more.
“What happens if I need my money back?”
That question changed the entire evaluation.
By now, Priya understood that a fixed indexed annuity is an insurance contract.
She understood that index-linked interest is calculated under specific contract terms.
She also understood that a 0% index-interest floor doesn't mean the contract guarantees a positive return every year.
But she hadn't yet examined the trade-offs involved in accessing her money.
And that was important.
Because retirement planning isn't only about how money grows.
It's also about when and how you can use it.
Suppose Priya is considering placing $200,000 into an FIA.
That's a meaningful amount of money.
Before making a decision, she needs to know what happens if:
She decides to retire earlier.
Her family experiences a medical emergency.
She wants to help her daughter.
She needs money for an unexpected expense.
Or she simply changes her mind.
Some FIAs allow a limited amount to be withdrawn annually without a surrender charge, subject to contract terms.
But withdrawing more than the permitted amount during the surrender-charge period may trigger charges.
Some contracts may also have market value adjustments that can increase or decrease the amount available upon certain withdrawals.
And if the annuity is held in a tax-deferred retirement account, distributions may have tax consequences.
For withdrawals before age 59½, an additional federal tax may apply unless an exception is available.
Priya was already 59, so her exact age and the timing of a withdrawal mattered.
But the broader lesson applied to everyone.
Principal protection is not the same as unrestricted access to principal.
And a 0% index-crediting floor doesn't necessarily mean the surrender value or every measure of contract value can never decline.
Fees, withdrawals, and contract provisions can affect the outcome.
Priya also learned that an annuity guarantee depends on the financial strength and claims-paying ability of the issuing insurance company.
An FIA isn't a bank deposit.
It isn't FDIC-insured.
And it isn't an investment directly held in the stock market.
So she asked a better question.
“How much of my retirement money can I reasonably commit for the long term without compromising the flexibility I need?”
That question was far more useful than asking whether the product was safe.
Because safety has more than one dimension.
Protection from negative index credits.
Liquidity.
Inflation.
Taxes.
Insurer risk.
And the ability to adapt when life changes.
Before considering an annuity, review:
The surrender-charge schedule.
Any free-withdrawal provisions.
Possible market value adjustments.
Rider costs and their effects.
The insurer's financial strength.
The tax treatment of withdrawals.
How much accessible cash you would retain outside the contract.
The goal isn't to avoid every financial commitment.
It's to understand what you're committing to.
Priya has learned what an FIA can do—and what it cannot do. Now she needs to decide whether it fits her retirement strategy at all. We'll examine how to compare an FIA with other retirement options and the questions to ask before signing a contract.
Before You Buy an Annuity, Ask These Questions
Priya didn't need someone to convince her that a fixed indexed annuity was the right choice.
She needed enough information to decide whether it was the right choice for her.
Four weeks ago, we met Priya.
59 years old.
Chief Human Resources Officer.
Approximately $1.35 million in retirement and investment assets.
Four years away from her intended retirement.
She had spent decades investing for growth.
Now she wanted to understand whether part of her savings should have different risk characteristics.
Someone introduced her to a fixed indexed annuity.
And she began asking questions.
First, she learned that an FIA is an insurance contract—not a direct investment in the stock market.
Second, she learned that index-linked interest may be limited by caps, participation rates, spreads, and other contract provisions.
Third, she learned that protection against negative index-crediting results doesn't eliminate surrender charges, liquidity restrictions, taxes, inflation, or insurer risk.
Now came the final question.
“Does this actually improve my retirement plan?”
Not:
“Is the illustrated interest rate attractive?”
Not:
“Is everyone else buying one?”
Not even:
“Can this product provide a guarantee?”
But:
“What specific financial objective would this contract help me accomplish—and what would I give up in exchange?”
Priya decided to compare her options before making any commitment.
She looked at bank savings and CDs.
She looked at bonds and other fixed-income investments.
She looked at her existing investment portfolio.
She examined different types of annuities, including contracts designed primarily for accumulation and those focused on retirement income.
Each option had different characteristics.
Bank deposits may provide liquidity and eligible deposit-insurance protection, but rates can change and returns may not keep pace with inflation.
Bonds may provide income but can fluctuate in value and involve interest-rate and credit risks.
Stock investments may support long-term growth but expose investors to market losses.
Fixed indexed annuities may offer contract-defined index-linked interest and protection against negative index-interest credits, but they can limit upside and restrict access to funds.
Income annuities may provide contractual payments, sometimes for life, but their liquidity, beneficiary provisions, and other features vary.
Priya realized she wasn't choosing between a good product and a bad product.
She was evaluating different financial trade-offs.
So she created a decision checklist.
SEVEN QUESTIONS TO ASK BEFORE BUYING AN FIA
1. What specific role would this annuity serve in my retirement plan?
2. How is interest calculated, and which caps, participation rates, spreads, and crediting periods apply?
3. Can those crediting terms change after the contract begins?
4. What fees, surrender charges, withdrawal restrictions, or market value adjustments apply?
5. How financially strong is the issuing insurance company?
6. What are the tax consequences, beneficiary provisions, and optional income features?
7. What alternatives have I compared, and why might this contract be more appropriate for my circumstances?
Priya didn't make a decision that afternoon.
And that wasn't a failure.
She had moved from being interested in a product to understanding how to evaluate it.
That's progress.
If you're considering an annuity, request the complete contract information, current crediting terms, surrender schedule, applicable fees, and any income-rider illustrations.
Ask for the assumptions to be explained.
Compare alternatives.
And evaluate the recommendation in the context of your complete retirement strategy.
Because a financial product should not be judged by the most attractive feature in a presentation.
It should be judged by how its benefits, limitations, costs, and risks align with your needs.
Priya has learned that the phrase “market-linked growth” doesn't explain how much interest an annuity may actually credit. Next, we'll follow another successful professional who receives two annuity illustrations with very different caps, participation rates, and crediting formulas: Fixed Indexed Annuity Caps, Participation Rates, and Crediting Explained.
From product curiosity to informed evaluation
“I need to understand what risks matter as retirement approaches.”
“Index-linked interest is not the same as receiving the full index return.”
“Protection and liquidity are different financial considerations.”
“I can evaluate whether this contract belongs in my retirement plan.”
Understand a Simplified Cap-Based Crediting Formula
Assumes a one-year point-to-point index strategy, a 0% index-interest floor, a cap, and no other crediting adjustments. Excludes dividends, fees, withdrawals, surrender charges, taxes, and other contract provisions. Actual terms vary and may change.
See where you stand. Talk to a licensed professional.
Priya Shah is a fictional composite created for education. All figures are hypothetical illustrations, not client results, quotes, or guarantees. Educational information only; not tax, legal, insurance, or investment advice. Product availability varies by state.